Understanding Financial Options with Poor Credit: A Complete Resource for Financial Recovery
When unexpected expenses arise and your credit history contains blemishes, locating funds quickly can seem like an impossible task. This comprehensive guide explores practical avenues for evaluating financial options when facing credit challenges, while introducing strategies that may help support your financial recovery and credit management.
Understanding Your Options When Credit Stands in the Way
Financial emergencies rarely announce themselves in advance. Whether confronting an unexpected medical bill, essential vehicle repair, or pressing household issue, the need for additional funds can become important. For those navigating poor credit histories, traditional banking channels may have more restrictive requirements, creating additional stress during already difficult moments.
The landscape of emergency lending has evolved considerably, however. Numerous financial products now consider applicants with different credit profiles, with lenders evaluating factors beyond credit scores. Understanding these options marks the first step toward evaluating your immediate financial needs while working toward stronger financial health ahead.
Key Considerations Before Seeking Emergency Funds
Before pursuing any funding source, taking time to evaluate your specific situation can help prevent costly missteps. Begin by assessing the true urgency of your need—some situations genuinely require funds within hours, while others allow for slightly longer searches that might yield more favorable terms.
Calculate precisely what you need to borrow. The temptation to request additional funds "just in case" can lead to unnecessary debt accumulation and higher repayment burdens. Remember that every dollar borrowed eventually requires repayment with associated costs.
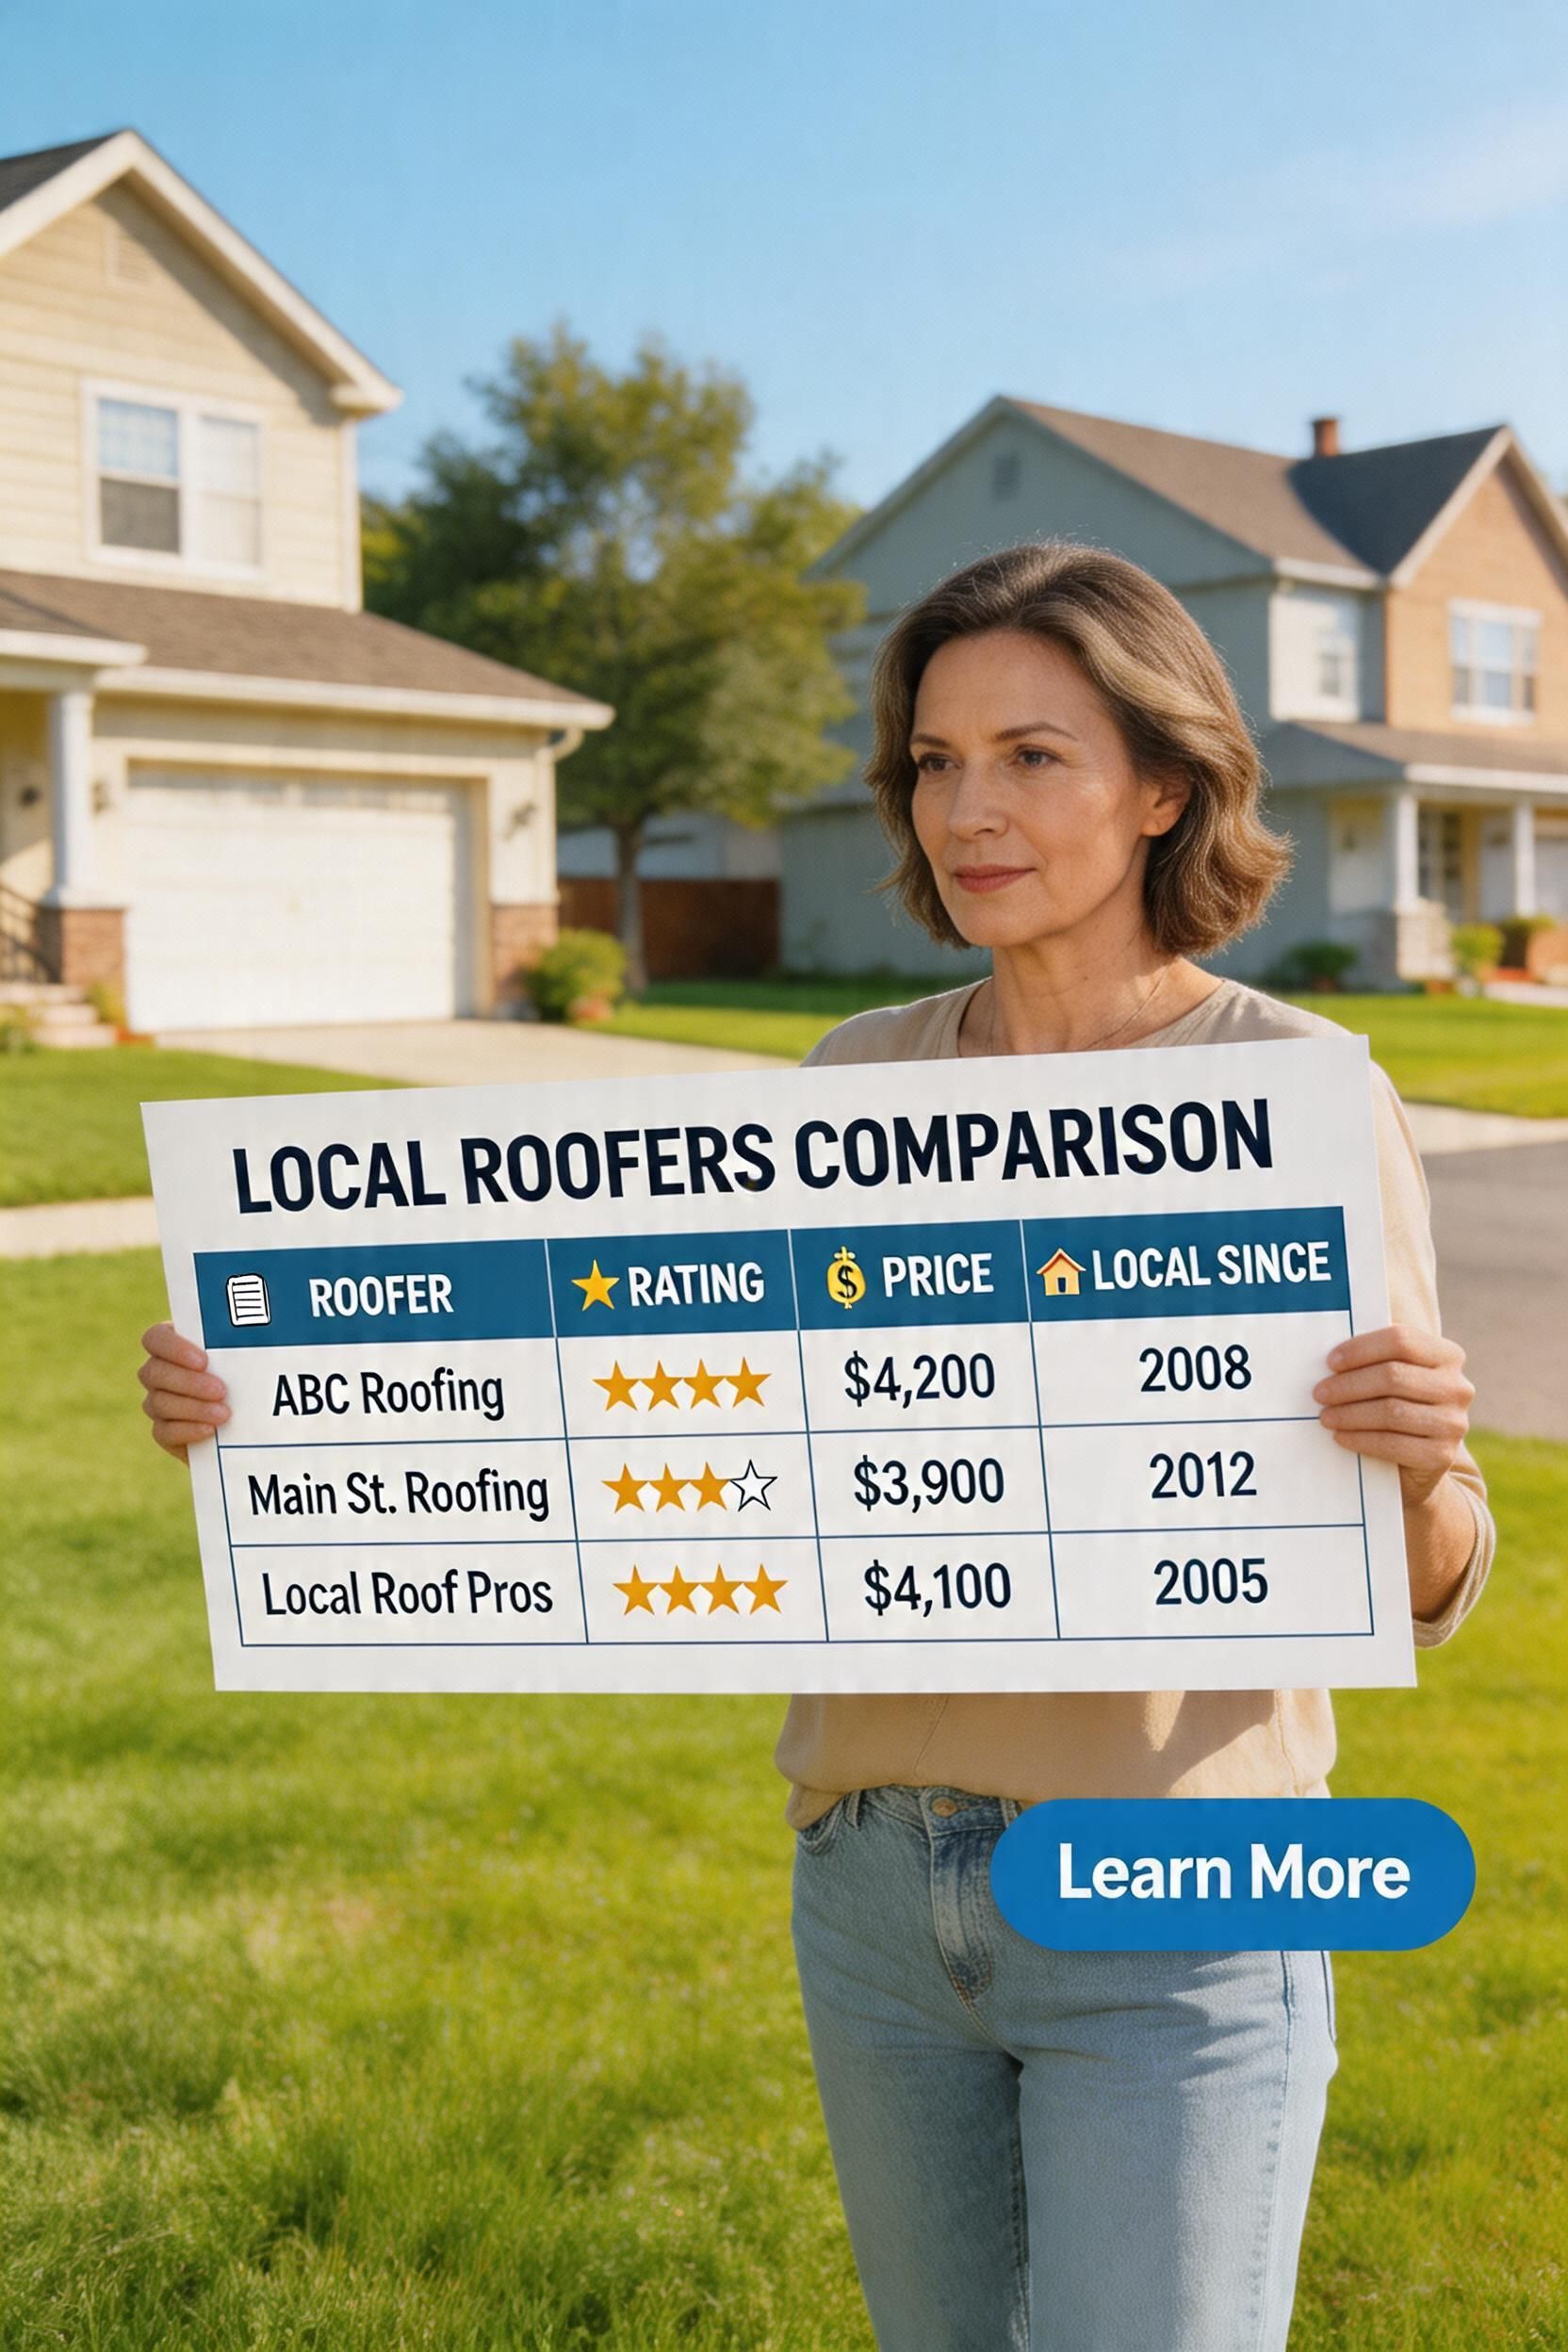
Finally, scrutinize the terms offered by potential lenders. Interest rates, repayment periods, and fee structures vary dramatically across the lending spectrum. Understanding these elements before committing can help you avoid agreements that might create more problems than they solve.
Immediate Cash Solutions for Bad Credit Situations
For those wondering how to explore emergency cash options with bad credit, several pathways exist beyond conventional banking. Online lending platforms have expanded access to financial products, evaluating applications through processes that may consider factors beyond credit scores. Income stability, employment history, and banking patterns may be considered depending on the lender, potentially providing additional options for applicants with different credit profiles.
Payday alternative loans from credit unions represent another resource to consider. These products emerged as an alternative to certain high-cost lending practices, offering smaller loan amounts with terms and fee structures that vary by institution. Credit unions exist to serve their members, and eligibility and lending requirements can vary between institutions.
Some employers now offer salary advances through specialized apps and services, allowing workers to access earned wages before scheduled paydays. These arrangements, when available and used judiciously, may provide an option for managing temporary cash shortages.
Understanding Loans Designed to Rebuild Credit
Beyond addressing immediate needs, certain financial products serve dual purposes—providing necessary funds while potentially supporting credit-building efforts. Loans to rebuild credit operate on a straightforward principle: consistent, timely payments may contribute to a positive payment history, depending on whether and how the lender reports information to credit bureaus.
These specialized products often feature different eligibility requirements, making them an option for borrowers whom traditional lenders might reject. The trade-off sometimes involves higher interest rates, so borrowers should carefully compare the total cost and terms before accepting an offer.
Some lenders structure these products specifically around credit building, with funds held in secured accounts until repayment completes. This approach may reduce certain lender risks and can involve different approval requirements depending on the product, while payment activity may be reported to credit bureaus.
Navigating Online Platforms for Credit Rebuilding Loans
The digital lending space offers access to credit rebuilding loans online, connecting borrowers with funding sources from the comfort of their homes. This convenience, however, requires careful navigation to distinguish reputable operators from less transparent providers.
Legitimate online lenders should provide transparent websites with clearly disclosed terms, interest rates, and fee structures before application submission. They may also provide accessible customer service and evaluate a borrower's ability to repay, which can help consumers avoid taking on unmanageable debt.
Reading third-party reviews across multiple platforms provides insight into others' experiences with particular lenders. Patterns of complaints regarding hidden fees, aggressive collection practices, or poor communication warrant serious caution. Taking time to research can help protect both your immediate financial needs and your long-term credit rebuilding objectives.
The Strategic Value of Credit Lines for Building Credit
Beyond traditional installment loans, credit lines to build credit offer distinctive features for financial rehabilitation. Unlike lump-sum loans, a line of credit functions as a reserve fund, accessible as needed with interest generally accruing on amounts actually drawn, depending on the product terms.
This structure can encourage responsible borrowing habits while providing an opportunity to manage revolving credit—a factor that can be considered by some credit scoring models. Many financial technology companies now offer specialized credit lines to build credit, targeting consumers who may not qualify for conventional credit cards.
The flexibility inherent in these products deserves particular attention. Maintaining an accessible credit line means having another potential option for future expenses, while interest charges may apply when funds are actually used. This combination of flexibility and potential cost considerations makes credit lines an option worth evaluating for those building both financial resilience and credit health.
Practical Steps for Securing Funds with Bad Credit
When time constraints press, having a clear action plan can streamline the process of evaluating emergency cash options for bad credit situations. Begin gathering documentation that demonstrates income stability and employment history—lenders focusing on your overall financial picture rather than credit scores may request this information.
Cast a wide net in your search. While multiple applications can temporarily affect credit scores through hard inquiries, the impact can vary depending on the type and timing of inquiries. Many online platforms now offer prequalification processes that may use a soft credit inquiry and therefore may not affect your credit score, although consumers should confirm the specific process with each provider.
Prioritize lenders who specifically indicate that they consider applicants with different credit profiles. These institutions may structure their underwriting to accommodate a range of credit histories, although approval, rates, and terms depend on individual circumstances.
Transforming Emergency Borrowing into Lasting Benefit
Viewing emergency borrowing as part of a broader financial strategy rather than merely necessity can change how you approach repayment. Each on-time payment may contribute to positive payment history when reported to credit bureaus. Managing credit responsibly can help establish habits that may be useful in future financial decisions.
Some lenders now integrate credit education directly into their platforms, offering tools helping borrowers understand how financial behaviors affect credit scores. Taking advantage of these resources can provide additional financial knowledge alongside borrowing decisions.
Setting up automatic payments, when feasible, can help avoid forgotten due dates while supporting consistent payment habits. Even modest automatic payments, maintained consistently over time, contribute to payment history when properly reported to credit reporting agencies.
Making Informed Decisions for Financial Stability
The journey from financial emergency to improved credit health requires thoughtful decision-making at each turn. Understanding available options—from emergency cash options for people with different credit profiles to specialized credit rebuilding loans online—can help consumers evaluate choices aligned with both immediate needs and long-term goals.
Remember that credit lines to build credit offer particular advantages for flexibility seekers, while installment loans provide structured repayment that some borrowers find easier to manage. The appropriate choice depends on individual circumstances, product terms, and financial needs.
By approaching emergency funding strategically, you can address today's financial needs while working toward greater financial stability. Each responsible borrowing decision can contribute to a stronger credit foundation over time, potentially expanding future options. The path from urgent need to financial resilience requires careful evaluation of both immediate costs and longer-term repayment considerations.